 By Prashant Chandra Panda* in Bhubaneswar, October 21, 2026: How do we make finance inclusive in India to ensure that no household in India remains excluded from banking, financial services and the use of financial technology which the banks provide for the convenience of their customers?
When we think of inclusive finance we think of the Jan Dhan Yojana a financial inclusion scheme of the Government of India launched on 28th August 2014. It is meant to facilitate financial inclusion of the people. It was open to all the Indian citizens who have ease and affordable access to financial services such as opening a bank account, remittance of money to people or to business, access to credit, insurance and pension services compared to the difficulties they faced in the 60s, 70s, 80s, and 90s till the Jan Dhan Yojana became operational.
This makes it possible to extend banking services to unbanked areas so that opportunities are created to enable more and more people particularly women to create accounts and make use of the banking services. This makes people aware of financial benefits and they stand to benefit when there is Direct Transfer of Money to farmers, to women now under the Subhadra Yojana, and to other beneficiaries like old age pensioners.
 We make use of the banking technology based on internet to receive money and transfer money. Opening of banking accounts is used as a leverage to make finance inclusive to include the citizens who did not have this benefit and make people financially literate. In India, technology for inclusive finance is built upon the India Stack, a digital public infrastructure consisting of Aadhaar (digital identity), UPI (digital payments), and Digi Locker (secure document storage).
This infrastructure, combined with a flourishing fintech ecosystem, enables low-cost, accessible financial services that reach previously underserved rural and low-income populations. Providing banking access to every village within a 5 km radius/hamlet of 500 households in hilly areas is one of the objectives which have been fully achieved in 27 states and eight UTs as on 31st March, 2025.
Financial literacy is the ability to understand and manage personal finances, including budgeting, saving, investing, and debt management. It is crucial for individual financial stability, empowerment, and participation in the formal economy, with the government and institutions like the RBI actively promoting it to increase financial inclusion and help citizens make informed decisions and avoid financial pitfalls. Each lender has its own method for analyzing a borrower’s creditworthiness.
They are —character, capacity, collateral, and conditions—when analyzing individual or business credit applications. Financial literacy guide introduces you to the seven core principles of managing your money: (i) earning, (ii) budgeting, (iii) saving and investing, (iv) management, (v) understanding credit, (vi) safeguarding your financial well being and (vii) financial planning.
Safeguarding your financial well being means one has to be aware of the risks involved; one may fall a prey into cyber risks, one may be cheated, money may get stolen, maybe it is used to buy wrong shares or put into wrong business. The earlier you start to become financially literate, the better off you’ll be.
 Financial literacy covers short- and long-term financial strategies. The strategy you use will depend on several factors, such as your age, investment time horizon, and risk tolerance. It is imperative to understand how to use financial products such as mortgages, student loans, health insurance, and self-directed investment accounts have grown in importance them responsibly.
It’s also important to know which investment vehicles are the best to use when saving for a financial goal like buying a home or for retirement. Other developments in finance, such as e-wallets, digital money, and P2P lending, can be convenient and cost-effective, but only if you know how to use them.
It is the most crucial to plan and save enough to provide an adequate income in retirement while avoiding high levels of debt that might result in bankruptcy, default, or foreclosure. For these day-to-day living expenses, living within your means, short-term borrowing, and long-term budgeting are essential components of being financially sound. You need to be financially literate to manage these and other essential financial realities as you go through life.
Interestingly in its report on “Economic Well-Being of U.S. Households in 2022” the U.S. Federal Reserve System Board of Governors mentioned that many Americans are not prepared for retirement. Twenty-eight percent indicated that they have no retirement savings, while about 31% of those not yet retired felt that their retirement savings were on track. Among those who have self-directed retirement savings, about 63% had low levels of confidence in their retirement decisions.
Current youth or millennial also carry large amounts of student loan and mortgage debt. In fact, in US 44% of them said they have too much debt. India is heading towards that direction. Fundamental financial concepts are poor among students pursuing higher education. Interestingly in US forty-three percent reported using expensive alternative financial services such as payday loans and pawnshops. More than half lacked an emergency fund to cover three months’ expenses, and 37% were financially fragile (defined as unable or unlikely to be able to come up with $2,000 within a month of an emergency).
A lack of personal financial awareness is creating widespread vulnerability to predatory lending in the period leading. The danger is more today. Earlier generations relied on cash, and only the relatively affluent had access to loans. Today’s consumers face a world that is both more convenient and more hazardous.
Credit Delivery: Priority Sector-Agriculture
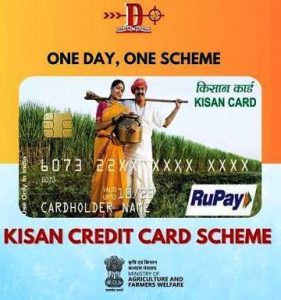 The Kisan Credit Card (KCC) is a single window facility for providing working capital as well as investment credit to farmers for cultivation, animal husbandry and fisheries. Literacy is essential for farmers because it improves agricultural practices, enhances access to information, and increases financial stability.
An educated farmer can adopt modern techniques, understand market trends, access government programs, and manage finances to become more productive, prosperous, and self-sufficient. Literacy also helps farmers improve their knowledge of sustainable practices and their legal and civic rights. By investing in financial literacy in rural areas, we not only equip farmers with knowledge but also unlock the full potential of agricultural finance in India.
Financial literacy for Micro, Small, and Medium Enterprises (MSMEs) is the ability to understand and effectively use a range of financial skills, including accounting, budgeting, and investment strategies, to ensure business growth, sustainability, and resilience. It is critical because it empowers owners to make informed decisions, manage risks, and successfully access funding.
MSMEs frequently face significant challenges in obtaining financing. Basics of accounting and book keeping tracking income, expenses and profitability are crucial. Financial planning and budgeting includes create realistic budgets, forecast future revenues and expenses, and develop strategic plans to achieve their business goals. From financial statements they need to track performance, spot trends, and make informed decisions based on data. Making timely debt repayments, keeping credit utilization ratios low, regular monitoring credit reports for accuracy help them to maintain good credit score.
Mentoring and coaching relationships can provide personalized guidance and support, helping business owners navigate financial challenges and make informed decisions. Government initiatives and policies like funding financial literacy programs, creating awareness campaigns, and integrating financial education help integrating towards the broader MSME support framework.
This may also be to help in the financial inclusion of the weaker sections of the society including women and other disadvantaged groups with the mainstream economics. Not only that. Availabilities of banking facilities in unbanked areas can be expected to facilitate financial integration of the rural and urban sectors of the economy.
The National Strategy for Financial Inclusion 2019-24 rightly points out “An inclusive financial system supports stability, integrity and equitable growth.”
*Former Prof. of Economics, School of Management, KIIT University, Bhubaneswar


Leave a Reply
Be the First to Comment!